 Skip to content


Class 4 impact-resistant shingles are usually worth pricing in Texas if you’re already replacing your roof and your insurer gives a real discount. They’re a weaker buy if the discount is small, or if getting it means signing away cosmetic hail coverage you’d want to keep. The answer comes down to three numbers and one form, and this guide walks through each.
Quick answer
- Class 4 is the top impact class under UL 2218. It’s a lab rating, not a promise that a shingle won’t be damaged.
- Texas insurers set their own discounts, so only your agent can give you the real number.
- Divide the extra roof cost by the yearly discount to get your payback time.
- Ask if the discount comes with a cosmetic hail exclusion before you sign anything.
- Check the exact product in the IBHS ratings. Class 4 products don’t all score the same.
What does Class 4 actually mean?
UL 2218 is a lab test that drops a steel ball on a roofing sample. There are four classes, and the balls run from 1¼ inches at Class 1 to 2 inches at Class 4, according to engineers from the Insurance Institute for Business and Home Safety (IBHS) writing in the National Roofing Contractors Association’s magazine. Each spot gets hit twice. Then inspectors bend the shingle and look at the back for cracks or tears under magnification. It’s pass or fail.
That last part matters more than most sales sheets admit. A steel ball isn’t a hailstone, and a pass/fail check on the back of a shingle says little about dents or lost granules on the side you can see. So a Class 4 label tells you the product passed a set test. It doesn’t tell you how good it looks after a real storm.
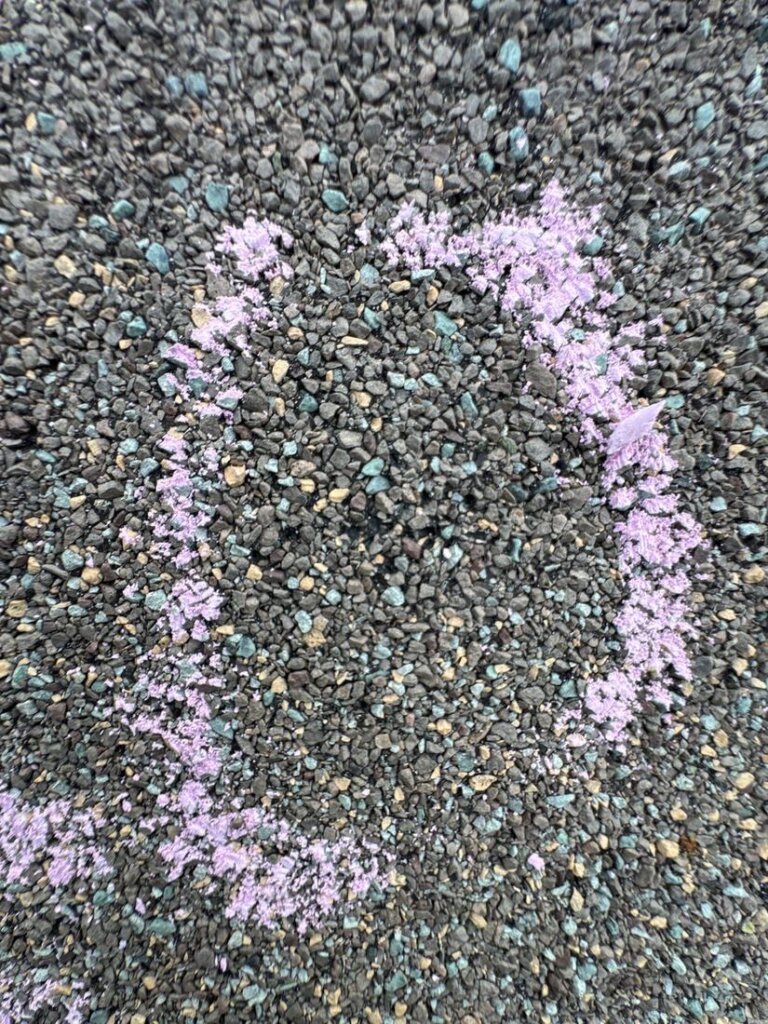
Do impact-resistant shingles work against real hail?
Often, yes, but the label alone won’t tell you which ones. IBHS built its own test because the older methods fall short. It buys shingles from retail stores, the same way a homeowner or roofer would, and scores damage from granule loss and dents up to a shingle that’s fully compromised. Its public ratings are based on 2-inch hail.
The November 2025 round covered a record 24 products. Most rated Good, and none earned Excellent. IBHS says it doesn’t recommend Marginal or Poor products in areas that get hail. Its interactive ratings tool lets you search by manufacturer, including GAF, CertainTeed, Owens Corning and IKO, and it lists a 2026 scorecard too. Look up the exact product name on your quote before you sign. We cover the wider material choice in our guide to the best roofing materials for Texas weather.
How much is the insurance discount in Texas?
Nobody can give you a statewide number. The Texas Department of Insurance (TDI) says each insurer sets its own discount for each class, along with its own testing, labeling and paperwork rules. TDI does say a Class 4 covering would get the highest credit. Any page quoting a flat Texas percentage is guessing.
Real-world figures exist, but treat them as examples. In a 2019 CBS Texas report, State Farm said upgrading could cut payments by up to 28 percent, and the story described a Class 4 roof that cost nearly $1,700 more and took over $400 a year off a USAA premium. That’s seven years old and from one insurer’s quote, so call your own agent before you use it.
Before you call your agent, ask these
- What’s my yearly discount in dollars for Class 4? For Class 3?
- Does it apply to the whole premium or only part of it?
- What paperwork do you need, and by when?
- Does the discount add a cosmetic damage exclusion or change my roof coverage?
The catch: the cosmetic hail exclusion
Most articles skip this, and it’s the question that can change the math. When Texas created optional Endorsement HO-145 in 1998, it was tied directly to the impact-resistant roof credit. The endorsement could go only on policies receiving that credit, and it was void unless the policyholder signed it.
Under that wording, the insurer doesn’t pay for hail damage that only changes how the roof looks. It still pays for hail damage that lets water through or stops the roof from doing its job. That’s a 1998 form, and today’s insurers write their own versions, so your policy’s wording is what counts. Check your own policy. This is general information, not legal advice.
Why does it matter? Dents and granule loss are the kind of marks a tough shingle can show after hail while still keeping water out. If your policy excludes cosmetic damage, you may be left with a marked-up roof and no claim. Some homeowners will gladly take that trade for a lower premium. You should just make it on purpose.
Are Class 4 shingles worth the extra cost?
Get two quotes for the same roof, one with a standard architectural shingle and one with a Class 4 product. Then get the yearly discount from your agent. Divide the first number by the second.
| Yearly discount | Extra roof cost | Payback time |
|---|---|---|
| $200 | $2,000 | 10 years |
| $300 | $2,000 | About 6.7 years |
| $400 | $2,000 | 5 years |
The $2,000 is an example for the math, not a price. Your quote and discount will differ, and premiums change from year to year.
The 2019 CBS example works out to about 4.25 years ($1,700 divided by $400). A premium discount can also shrink or change if you switch insurers, so don’t count on it lasting the life of the roof.
Here’s how we’d think about it for your situation:
| Your situation | Our take |
|---|---|
| Replacing the roof anyway, solid discount, no new exclusion | Usually worth it. You only pay the price gap between the two shingles, and the discount starts paying that back. |
| Replacing the roof anyway, solid discount, cosmetic exclusion added | Run the numbers, then decide if you can live with hail marks you’d pay to fix yourself. |
| Small or no discount | You’re paying for toughness alone. It can still make sense if hail is common where you live, but it won’t pay for itself through premiums. |
| Selling within a few years | Payback probably runs past your stay. A good standard architectural shingle may be the better spend. |
| Roof is fine today | Don’t replace a sound roof just for this. Plan for it at your next replacement. |
How much hail does your part of Texas really get?
Discounts aren’t the only payoff, because a tougher roof matters more where hail shows up often. For the Houston area, our count of 10 years of NOAA reports found about 1.9 days a year with golf-ball hail or larger somewhere across five counties. Those reports cover a wide area, so one house sees far fewer. Still, over the life of a roof, that adds up to a real chance of a serious hit.
If you’re not sure what a past storm did to your roof, start with our guide on how to spot hail damage.
What does a Class 4 roof not do?
- It doesn’t make the roof hail-proof. IBHS’s top result in the 2025 round was Good, and nothing reached Excellent.
- It doesn’t remove your deductible. On a 2% wind and hail deductible with a $300,000 dwelling limit, you’d pay the first $6,000 of a covered claim. See how that works in our Texas roof claim guide.
- It doesn’t fix a bad install. Damaged decking, poor flashing or weak ventilation will hurt any shingle. On a two-story hail job in Pearland, we cut out and replaced damaged decking before the new roof went on.
- It doesn’t guarantee a discount. Without the right label or paperwork, you can pay for the shingle and miss the credit.
How do you get the discount in Texas?
- Call your agent before you pick a shingle. Get the discount in dollars and the paperwork rules.
- Pick a product by exact name, then check it in the IBHS tool.
- Have the quote list the product name and its UL 2218 class in writing.
- Keep a wrapper or label from the bundles. TWIA requires a label showing the lab mark, the class, the manufacturer, the year made and the brand name. See TDI’s roofing discounts page.
- Ask the roofer to fill out TDI Form PC068 after the install. TWIA requires it. Private insurers may use their own form.
- Send the paperwork to your agent, then check your next renewal to confirm the credit shows up.
What we’ve seen on Pearland hail roofs
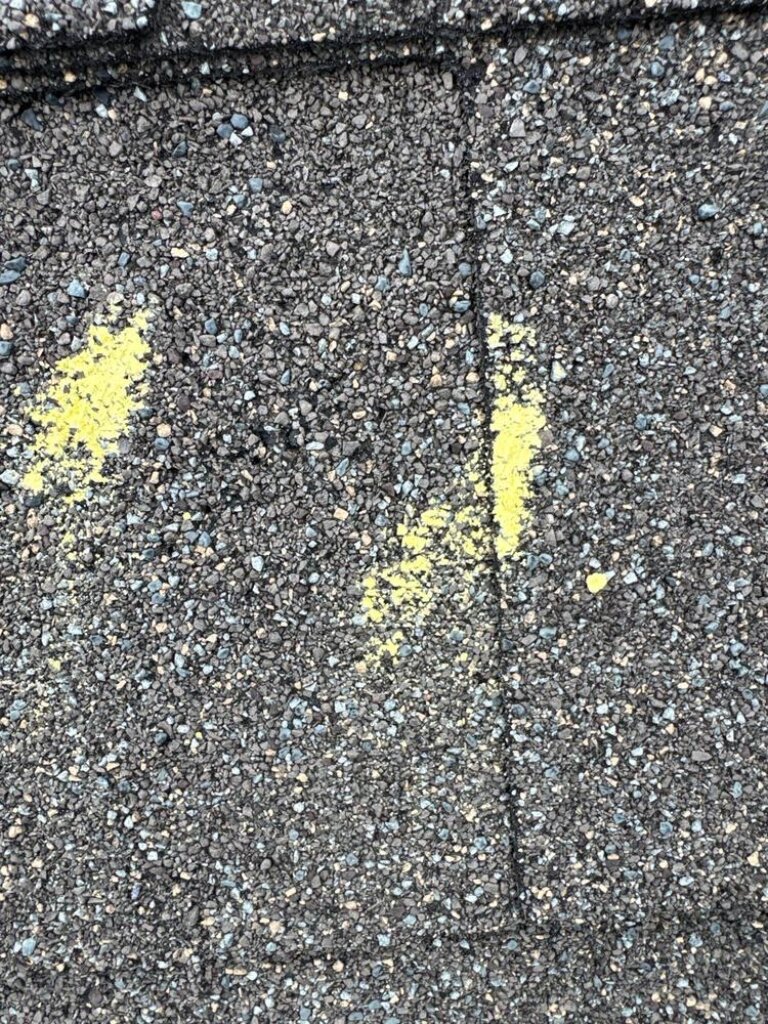
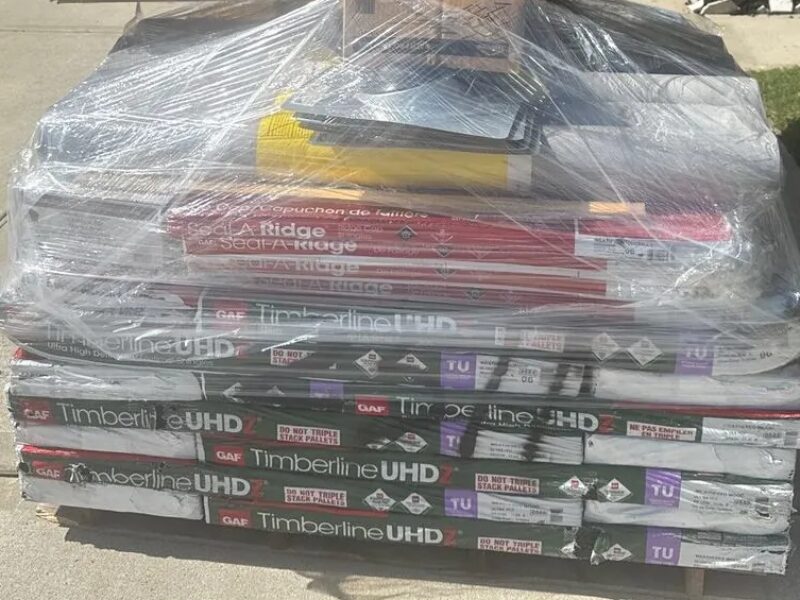
Our real project photos show why this question comes up. On a single-story hail roof in Pearland, bruising ran across the shingle field and we marked it for the adjuster. The new roofs on our Pearland hail jobs used GAF Timberline shingles. Those project pages don’t list an impact class, so don’t read them as Class 4 examples.
We install GAF, CertainTeed, Owens Corning and IKO shingles, and we recommend a repair when a repair is enough. If you’re comparing options, ask for a quote that prices each shingle separately. Our Texas roof replacement cost guide explains what else moves the price, and financing through third-party lenders is available if you need to spread out the cost.
Frequently asked questions
How much more do Class 4 shingles cost?
It varies by product, roof size and market, so a written quote is the only reliable number. The one dated example we can source is a 2019 CBS Texas report of nearly $1,700 more on one Texas home. Ask a roofer to price the same roof both ways, so the difference is the shingle alone.
What is the Texas impact-resistant roof certificate?
That’s TDI Form PC068, the Impact-Resistant Roofing Installation Form. The contractor fills it out after installation, and it goes to the policyholder or agent. TWIA requires it for its credit. Private insurers may accept it or use their own form, so ask your agent which one they want.
How do I know if I have an impact-resistant roof?
You usually can’t tell by looking, because a rating is about the product and not its appearance. Check your roofing contract, invoice, any PC068 form and your policy’s declarations for a roof credit. If you have none of those, ask your original roofer or insurance agent which product was installed.
Is Class 3 good enough for a Texas discount?
Sometimes. TDI says products rated Class 1 through 4 can qualify under TWIA’s rules, with Class 4 receiving the highest credit, and private insurers set their own terms. Ask your agent for the dollar discount at each class, then compare that with the price gap between the two shingles.
Can I get a discount on a roof that’s already installed?
Possibly, if you can prove what’s up there. Your insurer decides what paperwork it accepts, and TWIA requires form PC068 and a labeled product. Find your invoice and product name first, then ask your agent. Without proof of the product and class, you may not qualify.
Replacing your roof and weighing Class 4?
We’ll inspect your roof and attic for free, document what we find with photos, and give you options in writing, with no pressure to decide on the spot. See our residential roofing and storm damage services.
Sources
- Texas Department of Insurance: Roofing discounts
- Texas Department of Insurance: Form PC068, Impact-Resistant Roofing Installation Form
- Texas Department of Insurance: Commissioner’s Bulletin B-0030-98 (Endorsement HO-145)
- IBHS: 2025 impact-resistant shingle ratings release
- IBHS: Shingle performance ratings
- IBHS: Interactive hail impact-resistant shingle ratings
- Professional Roofing (NRCA): “Hail no” by IBHS engineers, March 2022
- CBS Texas: Higher-priced shingles could save North Texas homeowners money (April 2019)


