 Skip to content


On a Texas roof claim, you pay your deductible and the insurer pays the rest of the covered cost. State law says the homeowner must pay it, and it’s a crime for a roofer to waive it, absorb it or hand it back as a rebate. This guide shows how to turn a percentage deductible into dollars and what the 2019 law really says. It also covers the legal ways to pay, and how to tell whether a claim is worth filing at all.
Quick answer
- Many Texas policies set the wind and hail deductible as a percentage of the dwelling limit. 2% of $300,000 is $6,000, whatever the roof costs.
- Insurance Code chapter 707 says the policyholder “shall pay any deductible.” A roofer can’t legally cover it for you.
- Any roofing contract of $1,000 or more paid from a claim has to carry a printed deductible notice.
- Your insurer can hold back the second check until you prove you paid. A financing contract counts as proof.
- If an honest estimate comes in under your deductible, a claim pays nothing.
How does a roof deductible work in Texas?
Your deductible is the part of each claim you pay before insurance pays anything. The Texas Department of Insurance (TDI) puts it simply: a deductible may be a dollar amount or a percentage, and on home policies it applies to each claim, not once a year like health insurance.
TDI’s own example uses two homes insured for $150,000 and the same $6,500 hail repair. Policy A has a $500 deductible and pays $6,000. Policy B has a 5% deductible, which is $7,500, so it pays nothing at all.
That second case catches a lot of Texas homeowners off guard. A percentage deductible is figured on your dwelling coverage limit, not on the size of the damage. Your roof could cost $9,000 or $25,000 to replace, and the deductible stays the same number.
You’ll find yours on the first page of the policy. TDI’s homeowners insurance guide calls it the declarations page, and it lists each coverage, its dollar limit and its deductible. Many policies show two deductibles: one for “all other perils” and a separate one for wind and hail. Roof claims after a storm use the wind and hail one.
What is your percentage deductible in dollars?
Find your Coverage A (dwelling) limit and your wind and hail percentage, then read across. The table is plain math, so it works for any Texas insurer.
| Dwelling limit | 1% deductible | 2% deductible | 5% deductible |
|---|---|---|---|
| $200,000 | $2,000 | $4,000 | $10,000 |
| $300,000 | $3,000 | $6,000 | $15,000 |
| $400,000 | $4,000 | $8,000 | $20,000 |
| $500,000 | $5,000 | $10,000 | $25,000 |
If your dwelling limit went up at renewal, your deductible went up with it. That’s worth a look every year, because a bigger limit quietly means a bigger share of every hail claim.
How much is the average roof deductible in Texas?
No state agency publishes an official average, so be careful with any single number you see online. What the public record does show is a move toward higher wind and hail deductibles.
The clearest example is the Texas FAIR Plan, the state’s insurer of last resort for people who can’t get a regular policy. Starting with policies effective on or after July 1, 2026, the FAIR Plan dropped its 1% wind and hail option. Existing 1% policies move to 2% at renewal, and the wind and hail choices now run from 2% to 5%.
On the coast, the picture is different again. TDI notes that homeowners policies along the coast may not cover wind and hail, so many homes in places like Galveston carry a separate Texas Windstorm Insurance Association (TWIA) policy with its own deductible. If you have two policies, you can have two deductibles on one storm.
A higher deductible does lower your premium. TDI says moving from a $500 to a $1,000 deductible can cut premiums by as much as 20 percent. The trade-off is how much cash you’d need on hand the day after a hailstorm.
Is it illegal for a roofer to pay your deductible in Texas?
Yes. TDI says plainly that it’s illegal for contractors to waive your deductible or help you avoid paying it. The rule comes from House Bill 2102, which took effect September 1, 2019. It did two things.
- It put the duty on the homeowner. The bill created Insurance Code chapter 707, which says a person insured under a property policy “shall pay any deductible” on a first-party claim.
- It made the roofer’s side a crime. It rewrote Business and Commerce Code section 27.02. A seller commits an offense if, without the insurer’s consent, they pay, waive or absorb the deductible, give a rebate or credit that offsets it, or help you avoid paying it “in any other manner.” Advertising or promising any of that counts too.
The offense is a Class B misdemeanor. TDI says violators could get up to a $2,000 fine and up to six months in jail.
One detail most articles get wrong: the 2019 bill struck the old wording that made it a separate crime for the homeowner to submit a claim built on those charges. The criminal offense in section 27.02 is now aimed at the seller. That doesn’t make a waived deductible safe for you. You’re still required to pay it under chapter 707, and TDI warns that a contractor who covers it by sending your insurer a padded estimate is sending false information, which would be fraud.
The notice your contract must include
- Any contract of $1,000 or more that’s expected to be paid partly or fully from a property claim must print a deductible notice in at least 12-point bold type.
- It starts: “Texas law requires a person insured under a property insurance policy to pay any deductible…”
- If a roofing contract tied to your claim doesn’t have it, ask why before you sign.
What do deductible deals look like?
Few roofers say “we’ll waive it” out loud anymore. The offers usually come dressed up as something else. TDI names the most common ones: an estimate written higher than the real cost so the extra insurance money covers your share, or a rebate or credit for the amount of your deductible.
Watch for these at the kitchen table:
- “We’ll work with your deductible” with no clear explanation of how.
- A cash-back offer, gift card or “credit” that happens to match your deductible.
- Free upgrades or extra work promised “out of the insurance money.”
- A quote that’s much higher than other bids for the same roof.
- A contract over $1,000 with no deductible notice on it.
TDI also points out the practical problem: a contractor who gives up thousands of dollars on your deductible usually makes it back by cutting corners or using cheaper materials. If you get an offer like this, TDI says to talk to your insurance company first. You can also report it to the Texas Attorney General’s Consumer Protection Hotline at 800-621-0508.
We don’t waive, absorb or rebate deductibles. When we work on a claim, we photograph the damage, write an itemized estimate and meet your adjuster on site. What you owe is the deductible your policy says, and nothing about that is negotiable with any honest roofer. Our storm damage team can walk you through the rest.
How do you prove you paid the deductible?
On a replacement cost policy, the money usually comes in two checks. The first is the estimate minus depreciation minus your deductible. The second, the recoverable depreciation, comes after the work is done. Section 707.004 lets your insurer hold that second check until it gets reasonable proof you paid your deductible.
The statute lists what counts as proof:
- A canceled check.
- A money order receipt.
- A credit card statement.
- A signed installment plan or other financing contract that requires full payment of the deductible over time.
Keep a copy of whatever you use with your final invoice. Paying in cash with no receipt makes this step harder than it needs to be.
Worked example (made-up numbers)
- Dwelling limit $350,000 with a 2% wind and hail deductible: $7,000.
- Adjuster’s replacement cost for the roof: $16,500. Depreciation for age: $4,500.
- First check: $16,500 minus $4,500 minus $7,000 = $5,000.
- Second check, after the roof is done and you show the $7,000 was paid: $4,500.
- Insurance pays $9,500 in total. You pay $7,000, about 42% of the job.
That last line is why a percentage deductible deserves attention before storm season, not after. For the full set of claim deadlines and steps, see our guide to the roof insurance claim process in Texas.
Is it worth filing a roof claim with a high deductible?
Sometimes it isn’t, and nobody should talk you into a claim that pays you nothing. TDI also reminds homeowners that filing small claims can raise what you pay for insurance later. Get an honest inspection and estimate first, then compare it with your deductible.
| Your situation | What usually makes sense |
|---|---|
| Estimate is below your deductible | Pay for the repair yourself. A claim pays nothing and still goes on your record. |
| Estimate is a little above your deductible | Weigh the small payout against a possible rate increase. Ask your agent how a claim would affect your premium. |
| Estimate is well above your deductible, damage across the roof | A claim usually makes sense. File promptly and keep photos of everything. |
| Older roof on an actual cash value policy | Do the math with depreciation. In TDI’s example, a 10-year-old $10,000 roof with a $2,000 deductible pays $5,000 on ACV instead of $8,000 on replacement cost. |
A missing shingle or a cracked pipe boot is usually a repair, not a claim. If that’s all we find, we’ll tell you so and quote the repair.
Legal ways to handle a large deductible
You can’t make the deductible disappear, but you can plan for it and spread it out.
- Finance it. A financing contract that pays the deductible in full over time is proof of payment under section 707.004. Our financing options come through third-party lenders and can include the deductible or upgrades alongside a claim. The lender sets the rates and terms.
- Use a card or a home equity line. A credit card statement is listed proof too. Compare the interest before you choose.
- Pick your deductible on purpose at renewal. A lower percentage costs more in premium. Ask your agent for quotes at 1%, 2% and a flat amount if your insurer offers one, and choose a number you could pay next month.
- Don’t pay everything up front. TDI advises against paying in full before the work starts and against making the final payment before the job is finished.
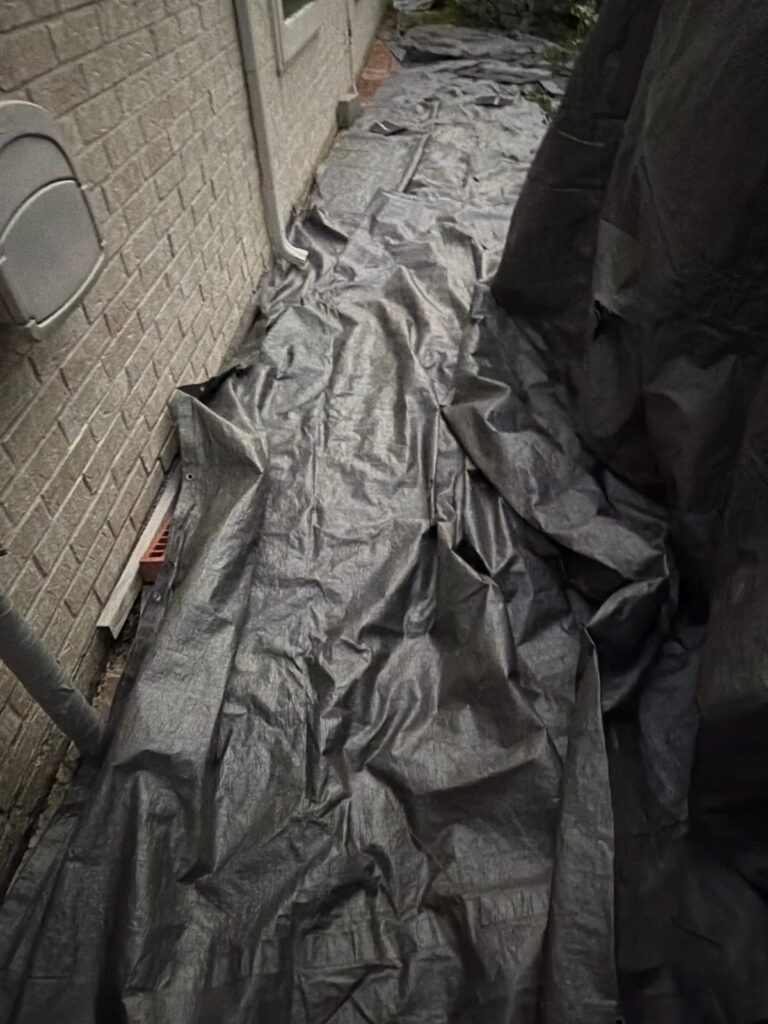
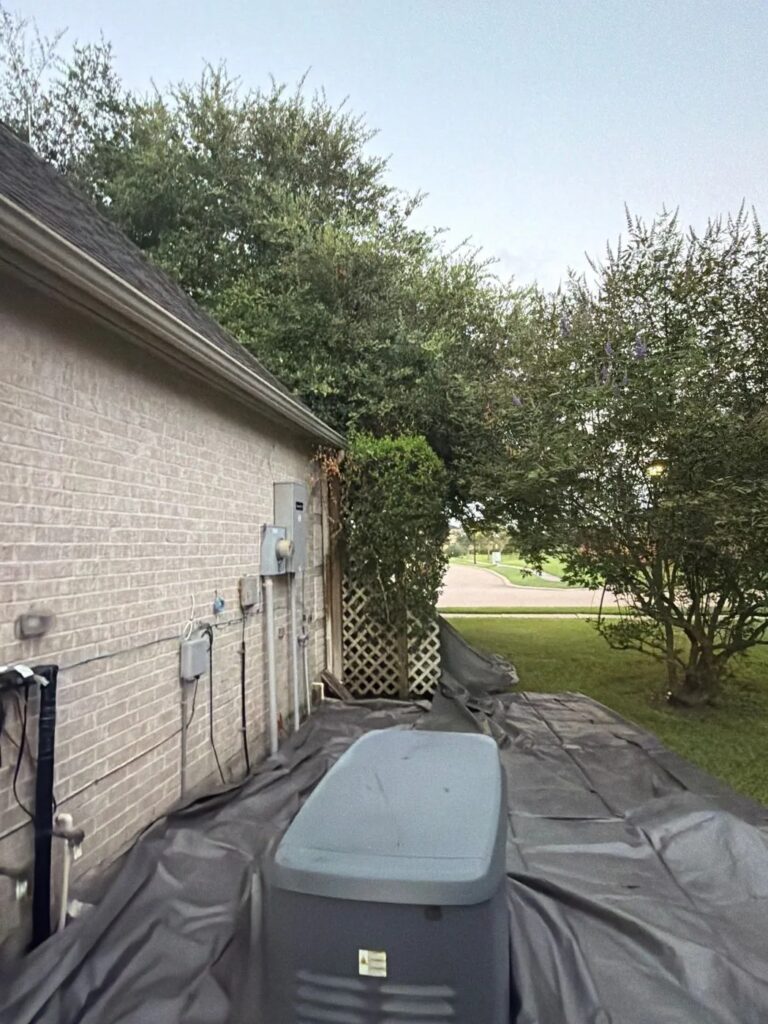
What a Pearland claim job looks like
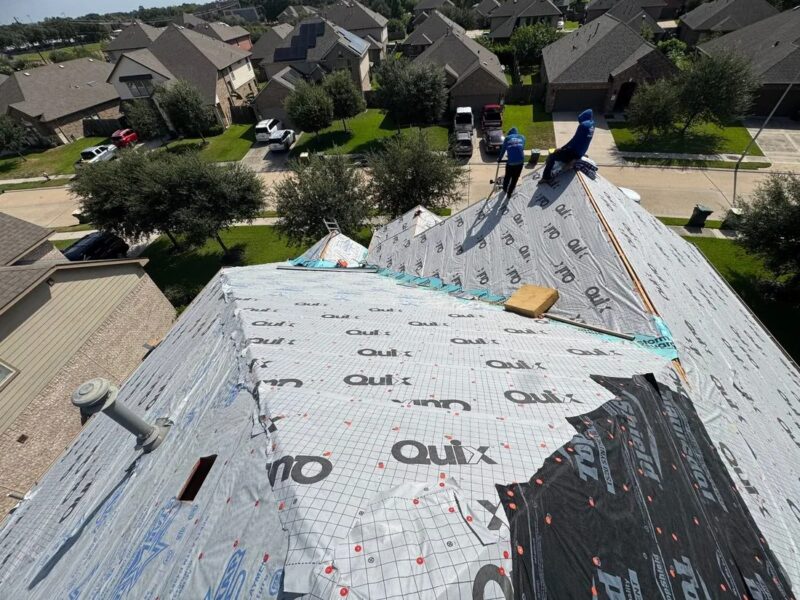
The photos above come from a large custom home in Pearland where hail damage led to a full replacement through an insurance claim. Before tear-off, the crew tarped the beds, patio and AC condensers. The deck was repaired where needed, the vent boot was replaced, GAF StormGuard leak barrier went down, and the roof was finished in GAF Timberline HD shingles with Seal-A-Ridge cap.
On a two-story Pearland home, also an insurance claim, damaged decking was cut out and replaced before the dry-in shown earlier. If you want to know what damage looks like before you call anyone, our guide to roof hail damage in Texas has photos from these same roofs.
Frequently asked questions
Do roofers cover the deductible in Texas?
Not legally. Since September 1, 2019, Business and Commerce Code 27.02 makes it a Class B misdemeanor for a seller to pay, waive or absorb your deductible, or give a rebate or credit that offsets it, without your insurer’s consent. Insurance Code chapter 707 also requires the policyholder to pay. A roofer who offers to cover it is breaking the law.
How much is a roof deductible?
It’s whatever your declarations page says. A flat deductible might be $1,000 or $2,500. A percentage deductible is figured on your dwelling limit, so 2% on a $300,000 limit is $6,000 and 5% is $15,000. Check the wind and hail line, since that’s the one a storm claim uses, and it’s often higher than your other deductible.
Can I get a new roof without paying my deductible?
Not on an insurance claim. The law requires you to pay it, and your insurer can hold back the depreciation check until you prove you did. What you can do legally is finance the deductible, pay it by card, or skip the claim and pay for the roof yourself if the claim math doesn’t work in your favor.
Does the deductible apply to every claim?
Yes. TDI notes that home deductibles apply to each claim, unlike health insurance deductibles that cover a year. Two separate hailstorms in one season can mean two deductibles. If you also carry a TWIA windstorm policy on the coast, that policy has its own deductible as well.
Can I finance my roof deductible?
Yes. Section 707.004 lists an installment plan or other financing arrangement that requires full payment of the deductible over time as reasonable proof of payment. We offer financing through third-party lenders, and it can cover the deductible alongside an insurance claim. The lender, not the roofer, sets the rate and terms.
What if the repair costs less than my deductible?
Then a claim pays nothing, and you pay for the repair either way. TDI also warns that small claims can affect your future premiums. Get the estimate first. If it’s under your deductible, it’s usually better to pay for the repair directly and keep the claim off your record.
General information, not legal advice. Check your own policy, and ask your agent or TDI (800-252-3439) about your situation.
Know your numbers before the next storm
A free inspection tells you what the damage really is and whether a claim makes sense against your deductible. We photograph everything, give you an itemized estimate and, if you file, meet your adjuster on site. If a repair is enough, we’ll tell you.
Sources
- Texas Legislature: H.B. 2102 (2019), enrolled text
- Texas Legislature: Insurance Code chapter 707, Payment of Insurance Deductible
- Texas Legislature: Business and Commerce Code chapter 27
- Texas Department of Insurance: Is it OK for a contractor to waive my deductible?
- Texas Department of Insurance: Roofing and insurance, know the law
- Texas Department of Insurance: State law cracks down on roof scams
- Texas Department of Insurance: What to know about deductibles
- Texas Department of Insurance: Homeowners insurance guide
- Texas Department of Insurance: What is windstorm insurance?
- Texas FAIR Plan Association: Deductible changes effective July 1, 2026


