 Skip to content


A roof insurance claim in Texas has six parts. You protect and photograph the damage, read your policy’s deductible and roof terms, report the claim, meet the adjuster, receive the first payment, then collect any held-back money once the work is done. Texas law sets deadlines for each step your insurer takes. This post walks through every step, the deadlines, how the two checks work, and what to do if the numbers come back low.
Quick answer
- Report hail or wind damage quickly. Your policy sets the deadline to file, and coastal TWIA policies allow one year from the date of damage.
- Your insurer has 15 days to acknowledge the claim and start investigating, then 15 business days after it has everything it needs to accept or reject it.
- Once it accepts, the insurer has 5 business days to pay.
- On replacement cost policies the first check is usually short the depreciation. The rest comes after the roof is finished and you show proof you paid your deductible.
- If you disagree with the amount, Texas policies usually offer appraisal, and you can file a complaint with the Texas Department of Insurance.
How does a roof insurance claim work in Texas?
Here is the whole process in order. The sections below explain each step and what Texas law requires of your insurance company along the way.
- Protect the house. Cover openings, catch drips and save every receipt for temporary repairs.
- Document the damage. Photos and video of the roof from the ground, the yard, the ceilings and the attic, before anything is thrown away.
- Read your policy. Find your wind and hail deductible, and whether the roof is covered at replacement cost or actual cash value.
- Get a roof inspection. Have a roofer confirm the damage is real and big enough to be worth a claim.
- Report the claim. Call or file online, write down the claim number, and keep a log of every call.
- Meet the adjuster. Be home for the inspection, and have your roofer there if you can.
- Review the estimate and first payment. Compare the adjuster’s scope with your roofer’s estimate line by line.
- Replace or repair the roof, pay your deductible, and send the final invoice to collect the held-back depreciation.
Step 1: Protect your home and document the damage
The Texas Department of Insurance (TDI) tells hail victims to file quickly, photograph the damage inside and out, and keep damaged items until the insurer says they can go. It also notes your policy may pay for temporary repairs, so keep receipts for tarps, buckets and anything else you buy.
Don’t make permanent repairs before the adjuster sees the roof. TDI’s storm recovery tips say this plainly. A tarp is fine. A new roof before inspection can leave the insurer with nothing to inspect.
Stay off a wet or steep roof. Good ground-level evidence includes dented gutters and downspouts, dinged metal vents, granules piled at the bottom of downspouts, damaged window screens, and water stains on ceilings. Write down the date of the storm. Every later step depends on it. Our guide to spotting roof hail damage in Texas shows what real hail hits look like.
Step 2: Read your policy before you call
Ten minutes with your declarations page answers the two questions that decide how much you’ll get.
What is your wind and hail deductible?
Many Texas policies use a percentage deductible for wind and hail, figured on the dwelling limit, not on the damage. On a $300,000 dwelling limit, a 2% deductible is $6,000. You pay that amount no matter who does the work. Texas law bars a contractor from waiving, absorbing or rebating it (Insurance Code chapter 707), and TDI confirms that any roofing contract of $1,000 or more paid from an insurance settlement has to include a notice that you owe the deductible.
Is your roof covered at replacement cost or actual cash value?
Replacement cost pays what it costs to put the roof back today. Actual cash value (ACV) subtracts depreciation for the roof’s age and condition. TDI’s own example shows how much that matters.
TDI’s example: a $10,000 roof with a $4,000 deductible
- Replacement cost policy, any roof age: the policy pays $6,000.
- ACV, 5-year-old roof (worth $8,500): pays $4,500.
- ACV, 10-year-old roof (worth $7,000): pays $3,000.
- ACV, 20-year-old roof (worth $4,000): pays $0.
Some policies use replacement cost for the house but ACV for the roof covering only. Look for a roof endorsement, and ask your agent if the wording isn’t clear.
Step 3: Get an inspection, then file the claim
A roofer’s inspection before you file tells you whether the damage is real and roughly what the job costs. If an honest estimate is below your deductible, a claim gets you nothing. We give free inspections of the roof, attic and any leaks, documented with photos, and we’ll tell you if a repair is enough. You can read more on our storm damage page.
How long you have to file depends on your policy, so check the “duties after loss” and “suit against us” sections. For coastal homes insured through the Texas Windstorm Insurance Association, state law sets the deadline: you must file a TWIA claim no later than one year after the damage happened. Whatever your policy says, filing within days keeps the evidence fresh and puts you ahead of the line of claims that builds up after a big storm.
When you file, write down the claim number and the adjuster’s name, and keep a log of every call: date, who you spoke with, what they said. TDI recommends this, and it saves you later if dates are disputed.
Texas deadlines your insurance company has to meet
Texas has a prompt payment law, Insurance Code chapter 542, that puts the insurer on a clock once you report the claim. TDI sums up the main deadlines on its claim deadlines page.
| Step | Insurer’s deadline | Where it comes from |
|---|---|---|
| Acknowledge the claim, start the investigation, request the documents it needs | 15 days after notice of the claim (30 business days for a surplus lines insurer) | Ins. Code 542.055 |
| Accept or reject the claim in writing | 15 business days after it receives everything it asked for | Ins. Code 542.056 |
| Extension if it needs more time | Must tell you why, then decide within 45 days | Ins. Code 542.056 |
| Rejection | Must state the reasons in writing | Ins. Code 542.056 |
| Pay an accepted claim | 5 business days after notifying you it will pay | Ins. Code 542.057 |
| Declared weather catastrophe | Deadlines extended by 15 days | Ins. Code 542.059 |
Two practical notes. The 15-business-day decision clock only starts once the insurer has every item it asked for, so send documents promptly and keep proof of what you sent and when. And after a large hailstorm, check whether TDI declared a catastrophe for your county, because that adds 15 days.
What happens when the adjuster inspects your roof
The adjuster checks each slope for hail hits, usually by marking a test square and counting the hits inside it, and looks for wind-creased or missing shingles, damaged vents and flashing, and interior leaks. Be home for the visit. TDI’s advice is simple: make sure the adjuster sees everything.
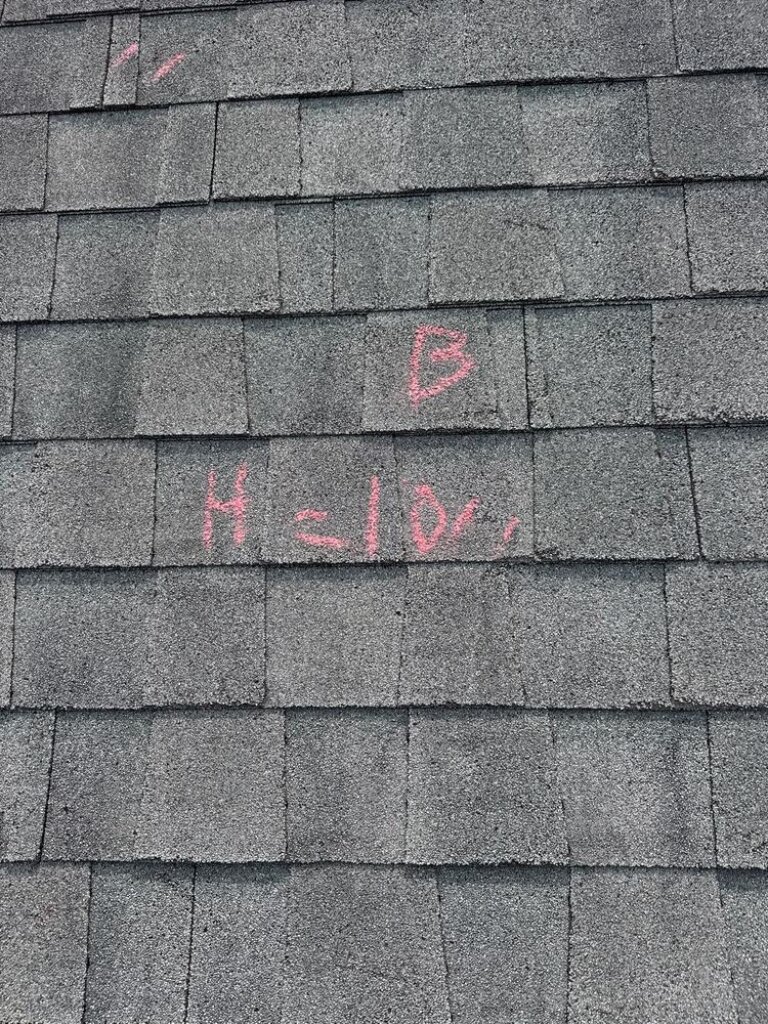
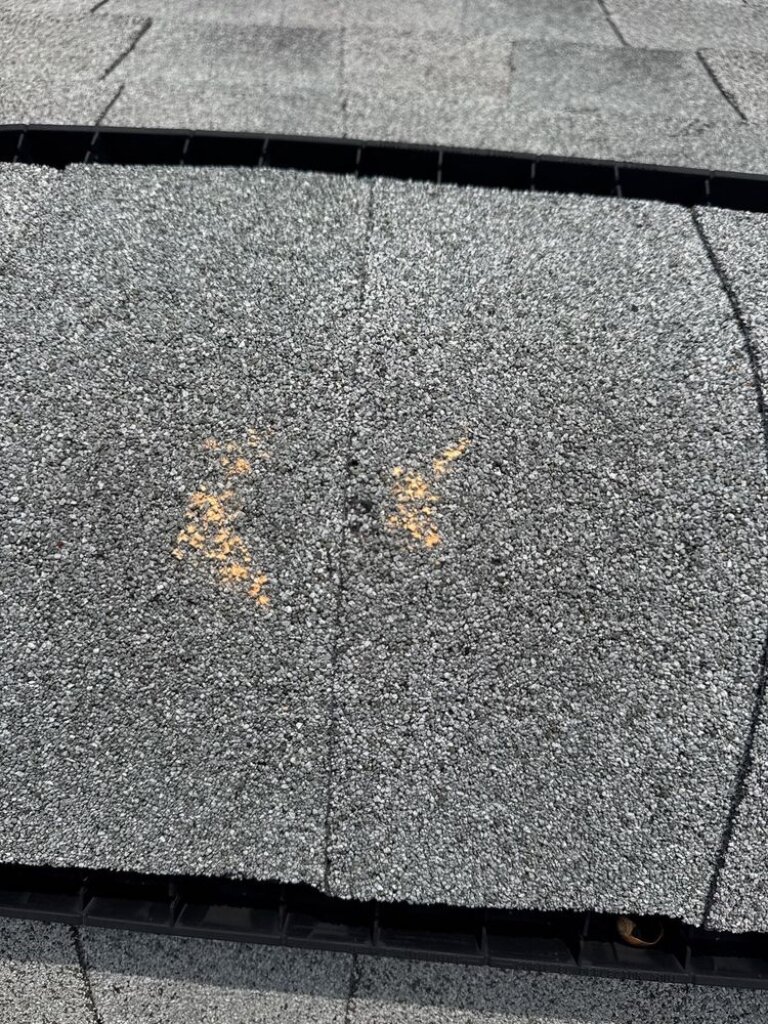
We meet adjusters on site and walk the roof with them so the damage we photographed gets seen. Know where the line sits, though. Texas doesn’t allow a roofer to act as your public adjuster, negotiate your settlement, or speak for you on coverage. A roofer can give an estimate and talk through the technical findings with the adjuster. Coverage decisions stay between you and your insurer.
What we documented on Pearland hail roofs
Our recent hail jobs in Pearland, Texas show what good claim documentation looks like.
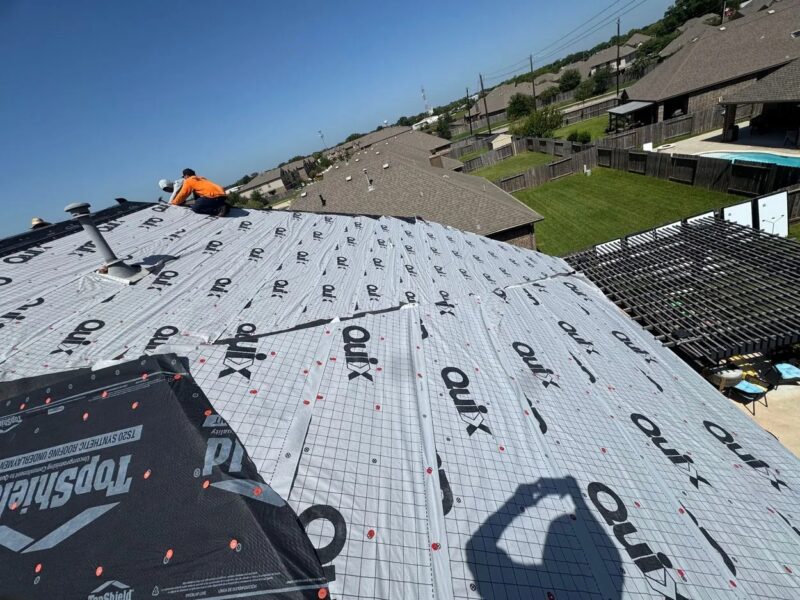
- On a single-story Pearland home, hail bruising was marked across the shingle field for the adjuster. After the claim, the roof was torn off to bare deck, the deck was inspected and re-nailed, and TopShield synthetic underlayment went down before new GAF Timberline HDZ shingles.
- On a large custom home, test squares were marked for the adjuster. Before tear-off, the beds, AC condensers and patio were tarped. The job added deck repairs, a new vent boot and GAF StormGuard leak barrier.
- On a two-story home with solar, the damage was documented for the adjuster, then the solar panels were detached and reset with every mount flashed into the new roof.
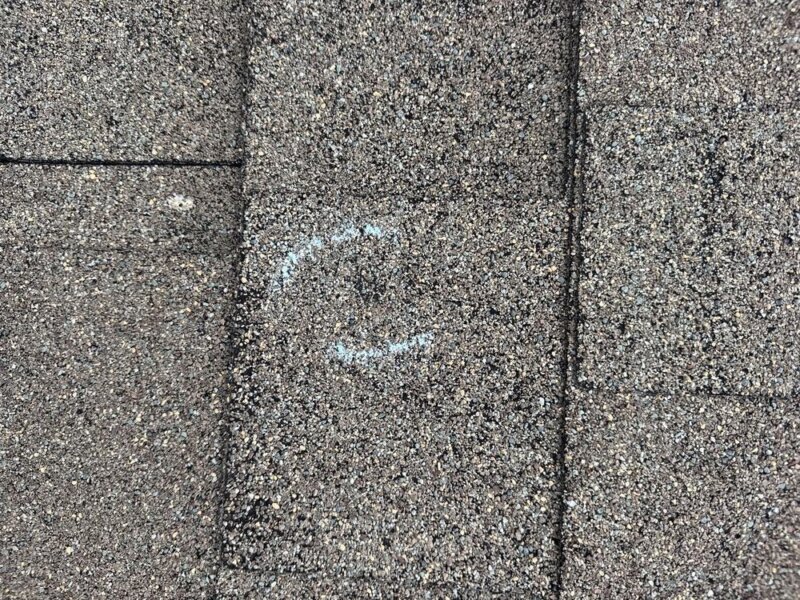
Line items like decking replacement, solar detach and reset, and leak barrier are where adjuster estimates and roofer estimates most often differ. Ask that each one is either in the scope or explained.
How the payments work: ACV, depreciation and the second check
On most replacement cost policies the money comes in two parts. The first payment is the replacement cost minus depreciation minus your deductible. The held-back depreciation, called recoverable depreciation, comes after the work is finished and you send the final invoice.
Texas lets the insurer hold that money until you prove you paid your deductible. Section 707.004 accepts a canceled check, a money order receipt, a credit card statement, or a financing contract that requires the deductible to be paid in full.
Worked example (made-up numbers)
- Dwelling limit $300,000 with a 2% wind and hail deductible: $6,000.
- Adjuster’s replacement cost for the roof: $18,000. Depreciation for age: $5,000.
- First check: $18,000 minus $5,000 minus $6,000 = $7,000.
- Second check, after the roof is done and you show the $6,000 was paid: $5,000.
- Insurance pays $12,000 in total, and you pay the $6,000 deductible. On an ACV roof, the payments would stop at $7,000.
If you have a mortgage, the check may also be made out to your lender, which then sets its own steps for releasing the money. Call the lender’s loss draft department early so the money doesn’t hold up the job. If the deductible is hard to cover in one payment, our financing options through third-party lenders can include the deductible. We don’t waive deductibles. For what a full replacement usually costs, see our guide to roof replacement cost in Texas.
What if the insurer pays too little or denies the claim?
A low first estimate is common, and it isn’t the end of the claim. TDI’s page on what to do if insurance isn’t paying enough lists these options. If the claim was denied outright, our guide to what to do when insurance denies a roof claim in Texas walks through the denial letter and your next steps.
- Tell the insurer why you disagree, in writing, with documents such as a contractor’s estimate and dated photos. The adjuster may have missed a slope, the vents or the decking.
- Ask for a re-inspection if damage was missed.
- Invoke appraisal if your policy has it and the dispute is over the amount. You and the insurer each hire an appraiser, and they pick an umpire. You pay your own appraiser and half the umpire. Check your policy for the deadline to demand it.
- Consider a licensed public adjuster. They charge fees, so get the fee in writing first.
- File a complaint with TDI if you think the company treated you unfairly. Use the homeowners complaint page or call 800-252-3439.
- Know the notice rule before any lawsuit. For weather claims, Insurance Code 542A.003 requires written notice at least 61 days before you file suit.
This is general information, not legal advice. Check your own policy, and talk to a Texas attorney about legal deadlines that apply to you.
Is it worth filing a roof claim?
Not always. If the damage is a few lifted shingles or a cracked pipe boot, the repair often costs less than a percentage deductible, and a claim pays nothing. An aging roof on an ACV policy can also leave little after depreciation, as TDI’s 20-year-old roof example shows.
A claim makes sense when hail or wind damaged enough of the roof that a repair won’t hold, and the replacement cost is well above your deductible. That’s why the inspection comes first. If a repair is enough, we’ll say so. Our residential roofing team handles both repairs and full replacements with GAF, CertainTeed, Owens Corning and IKO shingles.
Frequently asked questions
How long does insurance have to pay a claim in Texas?
Once your insurer tells you it will pay all or part of a claim, Texas Insurance Code 542.057 gives it 5 business days to send the money. Before that, it has 15 business days after receiving all requested documents to accept or reject the claim, or 45 more days if it notifies you that it needs more time. A declared weather catastrophe adds 15 days.
How long do you have to file an insurance claim in Texas?
For most homeowners policies the deadline is in the policy, so check the “duties after loss” section. Coastal homes with TWIA wind and hail coverage must file within one year of the date of damage under Insurance Code 2210.573. Whatever the deadline, report storm damage as soon as you can. Late reports make it harder to prove which storm caused the damage.
Can I file an insurance claim to replace my roof?
Yes, if a covered event such as hail or wind damaged it. Homeowners policies don’t pay for wear and tear or old age, so a worn-out roof with no storm damage isn’t a claim. Whether you get a full replacement or a repair depends on how much of the roof is damaged and on your policy’s terms.
Can a roofer handle my insurance claim for me?
Not in Texas. Insurance Code 4102.163 bars roofers from acting as public adjusters or negotiating your settlement. A roofer can inspect, photograph the damage, write an estimate and walk the roof with your adjuster to discuss technical findings. If you want someone to negotiate for you, that has to be a licensed public adjuster or an attorney.
Do I have to pay my deductible on a roof claim?
Yes. Texas law makes it illegal for a contractor to waive, absorb or rebate your deductible, and your insurer can hold back recoverable depreciation until you prove you’ve paid it. If paying it at once is hard, financing through a third-party lender is a legal way to spread it out.
Get your roof inspected before you file
We’ll inspect your roof, attic and any leaks for free, photograph what we find, and tell you honestly whether it’s a claim, a repair or neither. If you file, we’ll meet your adjuster on the roof. Our Texas service area is open Monday through Friday, 8 AM to 6 PM.
Sources
- Texas Department of Insurance: Insurance claim deadlines
- Texas Legislature: Insurance Code chapter 542, Prompt Payment of Claims
- Texas Legislature: Insurance Code chapter 542A, Certain Consumer Actions Related to Claims for Property Damage
- Texas Legislature: Insurance Code chapter 707, Payment of Insurance Deductible
- Texas Legislature: Insurance Code chapter 2210, Texas Windstorm Insurance Association
- Texas Department of Insurance: Hail damage tips to file an insurance claim
- Texas Department of Insurance: Storm recovery tips
- Texas Department of Insurance: Replacement cost or actual cash value
- Texas Department of Insurance: Roofing and insurance, know the law
- Texas Department of Insurance: What if my insurance isn’t paying enough?
- Texas Department of Insurance: Homeowners and renters insurance complaints


